
State Farm Denied My
Roof Claim: What Illinois
Homeowners Can Do Next
A denial or a low payment is State Farm's reading of one inspection. Here's what Illinois requires State Farm to put in writing and which step fits the reason it gave.
Free Storm Damage Roof Inspection
We dispatch a Haag-certified inspector to your address, same day in most cases.
"Donte Dacres provided outstanding service. He made the call to my insurance company with TOTAL professionalism."
Judith W."I was very worried about storm chaser roofers. Matt was patient and explained the whole process. He worked with me and my insurance company throughout."
Ram P."My insurance company said they would not cover my whole roof. C&N demanded a second insurance appraisal and BINGO! My re-roof was approved."
Michael G."Damian was incredibly helpful, especially with navigating insurance and the appraisal. The crew was efficient and got the job done quickly."
Alicja S.State Farm's own claims page says wind, hail, fire, and lightning damage to a roof is typically covered, and wear and tear, rot, deterioration, and workmanship typically aren't. A denial usually turns on which side of that line the inspection put your roof. Illinois rules require a written explanation that cites the policy provision, so start with the letter.
Before the adjuster comes, see what your photo shows.
Photograph the gutters, vents or shingles. We circle what we seem to see, so you know what a closer look is for.
Free. 30 seconds. No signup.
This AI only looks for storm and roof damage, and it isn't perfect. Think of it as a good starting point for a conversation.
Your browser shrinks the photo and removes the location data before it leaves your device. Privacy details.
Want to check recent storms near you? Your city only.
We never ask for a street address here, and the city stays in your browser.
Want us to get an inspector over, as soon as tomorrow in most cases?
A free inspection puts someone on the roof with a hand on the shingle. The report is yours to keep.
Storm reports reached Chicagoland on October 16, 2026: 49 mph gust.
Your policy sets its own deadline to report the damage, so check your declarations page. We'll document the roof and walk you through what happens next, in plain English.
Source: O'Hare (ORD) airport observations, October 16, 2026: peak wind 43 knots (49 mph) at 4:53 p.m.
What Illinois Requires in a State Farm Denial
When a company denies a first-party claim or settles for less than you claimed, Illinois requires a reasonable written explanation within 30 days after it completes its investigation and determines liability. The explanation has to clearly set out the policy definition, limitation, exclusion, or condition behind the denial, and it must come with notice that the Illinois Department of Insurance is available (50 Ill. Adm. Code 919.50(a)(1)). A company also can't deny a claim on information from a phone call or interview unless that conversation is documented in the claim file.
Failing to promptly provide a reasonable and accurate explanation of the policy or legal basis for a denial or compromise settlement is on the Insurance Code's list of improper claims practices, when done without just cause (215 ILCS 5/154.6(n)). If your letter says only "wear and tear" or "no hail damage," ask State Farm in writing for the provision it applied and the inspection findings behind it.
Where State Farm Draws the Line on Roof Damage
State Farm's home and property claims page lists roof damage as typically covered when it comes from wind, hail, fire, or lightning, including damage from a downed tree. It lists wear and tear, rot, deterioration, and workmanship (improper installation or repairs) as not typically covered. Your policy controls, and the page says to check it or ask your agent.
State Farm's roof claims page says a claim handler may help explain the difference between normal wear and aging and damage from a hailstorm. It names common characteristics of hail damage: random damage, impact marks, and, on wood roofs, splits with sharp edges. Those are the observations an inspection report should record, slope by slope, with photos. Our guides on what hail damage looks like on a roof and what to do when the adjuster says no damage go through them.
The dispute is about cause, so the strongest material is evidence of cause. That means dated photos close to the storm, the date of loss tied to a recorded storm (our 2026 storm report and storm map list recorded events), and a written inspection report with the findings by slope.
A Low Payment Is Not a Denial
Many State Farm roof disputes are payment disputes on a covered claim. State Farm explains on its own site that an actual cash value settlement subtracts depreciation for age, wear, and condition, that some replacement cost policies start with an actual cash value payment and pay the rest once the work is complete (time limits may apply), and that some policies settle individual items, such as roof or siding claims, differently from the rest of the house (State Farm Simple Insights, April 16, 2026). The Illinois Department of Insurance's claims guide says the same thing in plainer words: a policy may pay actual cash value on your roof and replacement cost on the rest of the home.
Two Illinois regulations help here. If a partial loss was settled on a written estimate prepared by or for the company, it must give you a copy on request, and if you then produce a higher written estimate it must review it and respond promptly in writing (50 Ill. Adm. Code 919.80(d)(7)(C)). On an actual cash value settlement it must provide, on request, the worksheets detailing each deduction for depreciation, including age, condition, and expected life (919.80(d)(8)(A)). Our guide to reading an adjuster's estimate shows what to check in them.
The Illinois Supreme Court on Depreciating Labor
In Sproull v. State Farm Fire & Casualty Co., 2021 IL 126446, a homeowner challenged State Farm's practice of depreciating labor when calculating actual cash value. The court found the policy ambiguous because it did not define actual cash value, construed it against State Farm, and held that depreciation could not be applied to the labor component (¶ 54). The court noted that the estimating software State Farm used can depreciate materials only, with labor depreciation a separate setting (¶ 53).
The holding rests on that policy's wording, and the case was a certified question, not a ruling on any particular roof claim. If your estimate shows depreciation on labor lines, an Illinois insurance attorney can tell you whether your policy language is the same. We can show you which lines carry depreciation in a copy of the estimate.
You Choose the Roofer, With or Without Select Service
State Farm's roof claims page says it is your choice who you select and hire to provide an estimate or complete repairs. Its Select Service Home Repair Program is voluntary and uses network service providers who match you with a contractor. State Farm lists direct payment to the service provider with no deduction for depreciation on replacement cost benefits, and a five-year workmanship warranty, as program benefits, and says those benefits apply only if you use the program. A denial doesn't change your right to use your own contractor.
State Farm's roof claims page also says what a roof repair estimate should include: quantities of all materials, including vents, flashing, and other wind or hail damaged items, labor charges, work specifications, approximate dates, payment procedures, permits, and warranty details. A contractor estimate that follows that list is easier to compare against State Farm's.
Complaints and the Suit Deadline
The Illinois Department of Insurance takes complaints in writing, passes a copy to the insurer, and lets the insurer 21 days to respond. It asks you to allow four to six weeks. It cannot act as your lawyer, decide the value of damaged property, or resolve a dispute that is only your word against the company's (Department complaint process).
The Department's 2025 Consumer Complaints Ratio Report lists State Farm Fire & Casualty Company with 1,211 homeowners complaints, 1,025 of them citing claims handling, against $2,221,802,527 of Illinois earned premium. That is 0.5451 complaints per $1 million of premium, against a homeowners industry mean of 0.4073. The count measures complaints received, not whether they were justified, and says nothing about a specific claim.
We did not retrieve State Farm's Illinois policy booklet, so read the suit-limitation section of your own policy for the deadline. Illinois tolls a policy's suit-limitation period from the date proof of loss is filed until the claim is denied in whole or in part (215 ILCS 5/143.1), and the company must tell you in writing, when it denies, how many days were tolled and how many remain (919.80(d)(8)(C)). The clock keeps running while you negotiate, so have an Illinois attorney confirm the date.
What We Do, and What We Don't
C&N Construction is a roofing contractor. We inspect, photograph, measure, and write estimates, and we attend re-inspections. We don't interpret your policy, argue coverage, or negotiate your settlement, because Illinois reserves that work for licensed public adjusters and attorneys. The callout below describes the free referral list. The full carrier guide is on our State Farm roof claim page, and the State Farm roof replacement requirements page covers what State Farm does and doesn't publish.
More help at this stage: the insurance claims process, whether a public adjuster fits your situation, your options after a denied roof claim, and the free storm damage roof inspection.
Free Roof Inspection
Haag certified. Report is yours to keep.
State Farm Denied or Underpaid Your Claim?
Two things, both free. First, a Haag-certified roof inspection with full photo documentation in the exact format carriers require, so any dispute starts from hard evidence. Second, our referral list of Illinois-licensed public adjusters who handle storm claims in Chicagoland, so if your claim needs a professional negotiator, you know who to call.
One line we never cross: we're roofing contractors, not public adjusters. We don't interpret your policy or negotiate your settlement, because Illinois law reserves that work for licensed public adjusters. What we do is document your damage to a forensic standard and connect you with the right licensed help. No cost, no obligation, and nothing to sign.
Full disclosure: we don't take referral fees from public adjusters, and no one on the list pays to be on it. Referrals are based on Illinois licensing and storm claim experience, and you're always free to hire any public adjuster you choose.
Get the Free Inspection + Referral ListIllinois roofing license #104.017643. GAF Master Elite (top 2% of contractors nationwide), Haag Certified Inspectors, BBB A+, OSHA certified crews. Work carries a 2-year limited lifetime workmanship warranty plus manufacturer-backed GAF system warranty options. Crews dispatch from the Hillside headquarters and work all of Chicagoland year round. See the work itself, our crews' own photos, on the recent work page.


On a recent insurance-funded roof, the carrier's first estimate missed 292 linear feet of gutter work. Our documented supplement recovered it: a $2,928 line added to the carrier's own estimate, with photos attached. And when we didn't complete a $13.81 downspout item on another project, the final invoice showed a $13.81 credit. Itemized in both directions, every time. The actual documents are on our billing transparency page.
Chicago Storm Pros is a service of C&N Construction, Inc. (cnroofs.com). Reviews, project counts, certifications, and ratings shown here reflect C&N Construction's work.
Got a State Farm Denial or a Low Estimate?
We'll inspect the roof for free, photograph and measure what we find, and give you the report to keep. We document damage. We don't interpret your policy or negotiate your settlement.
Get My Free InspectionOr call (708) 847-5095
What damage looks like when it's documented
Every photo is from a real C&N job. The circles mark what our team flagged.
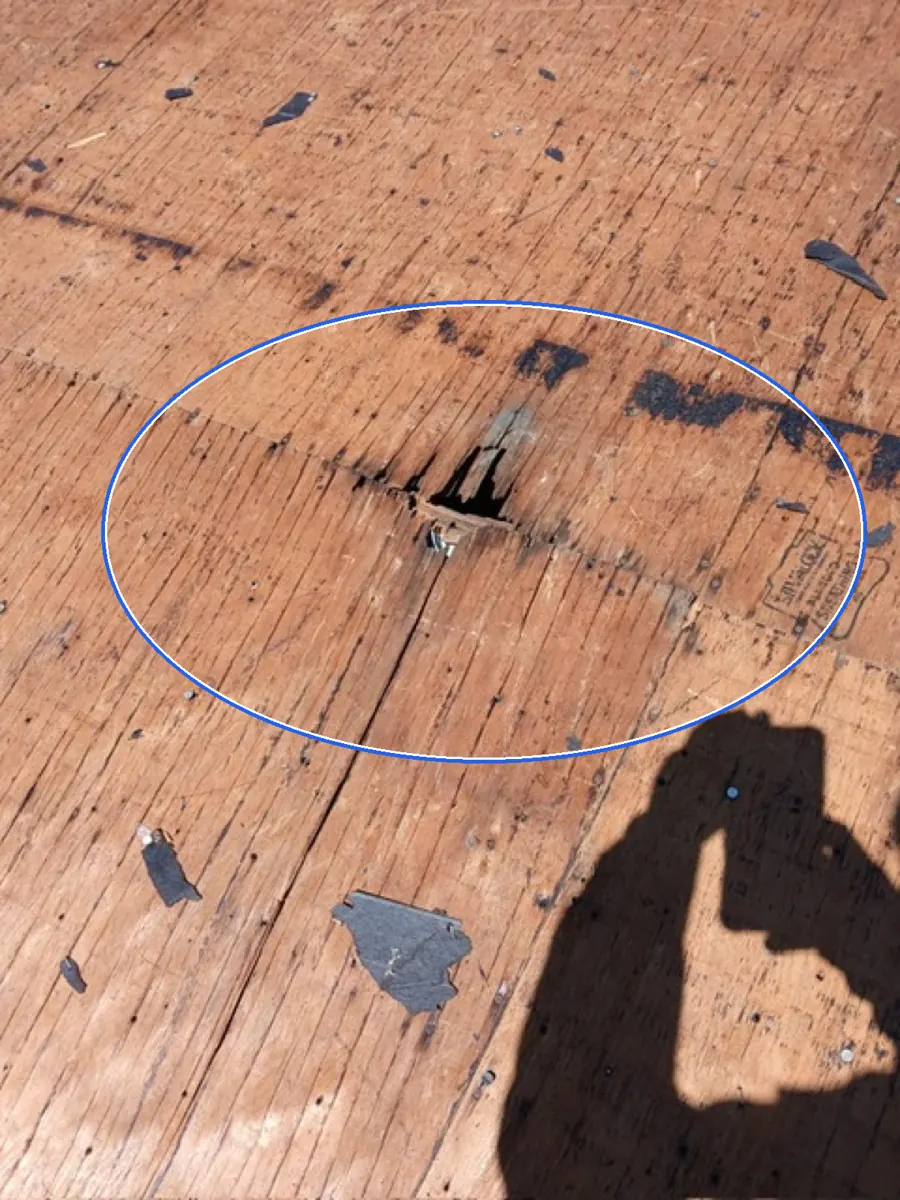
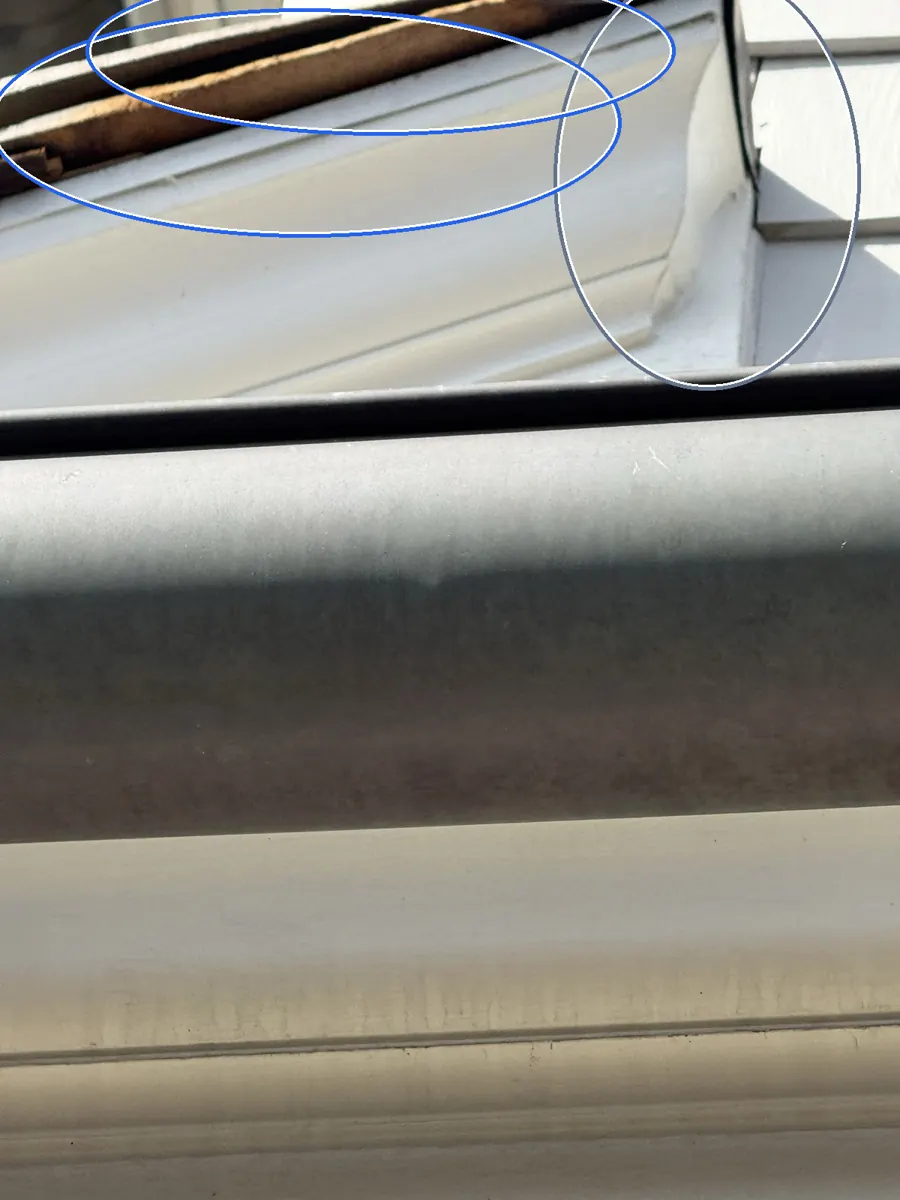
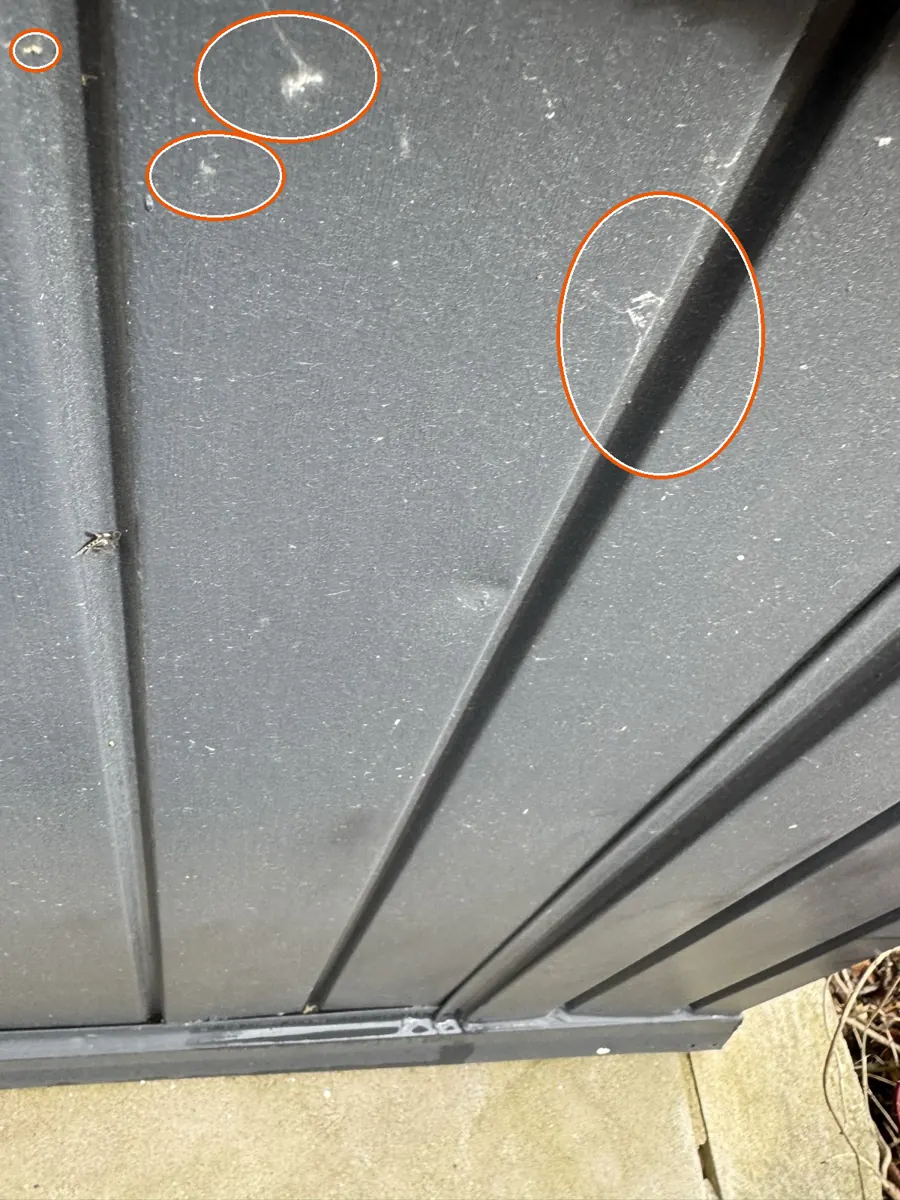
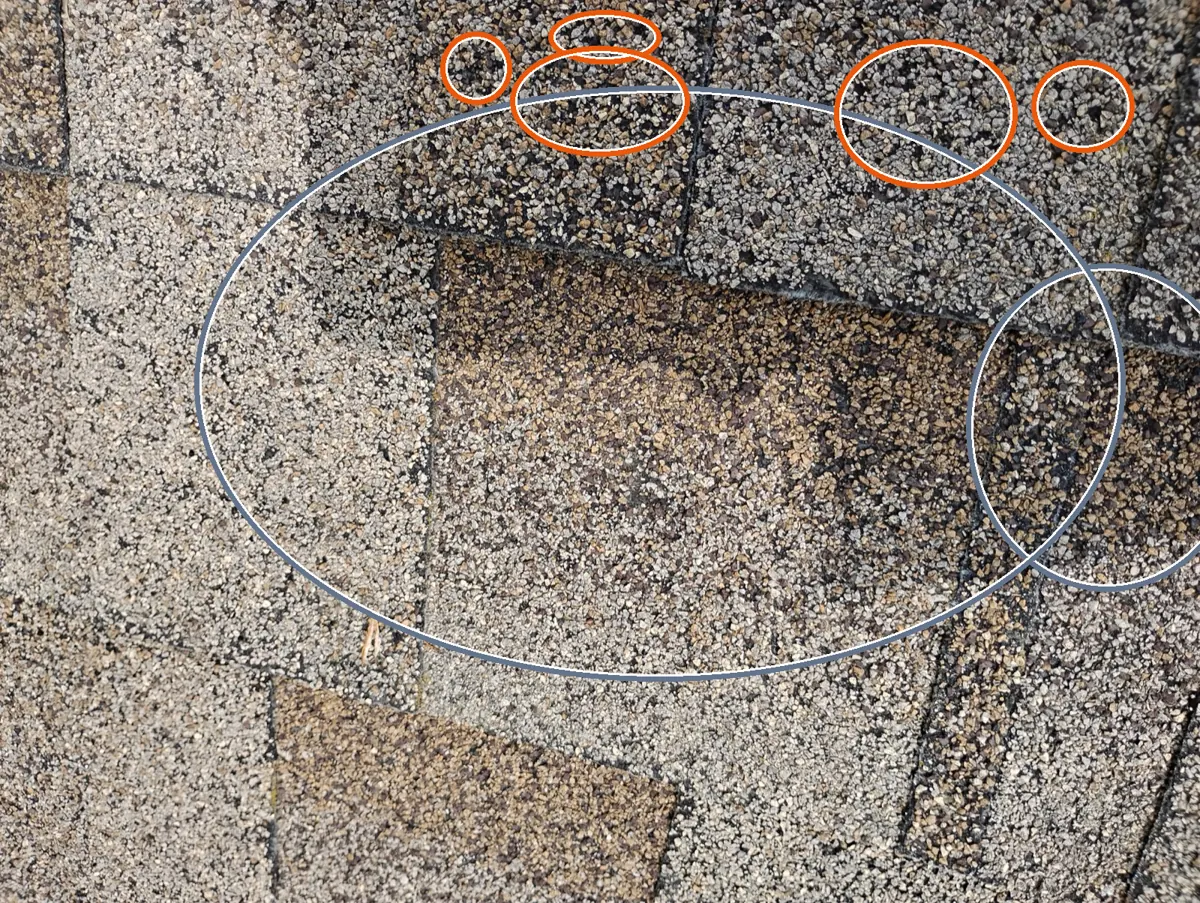
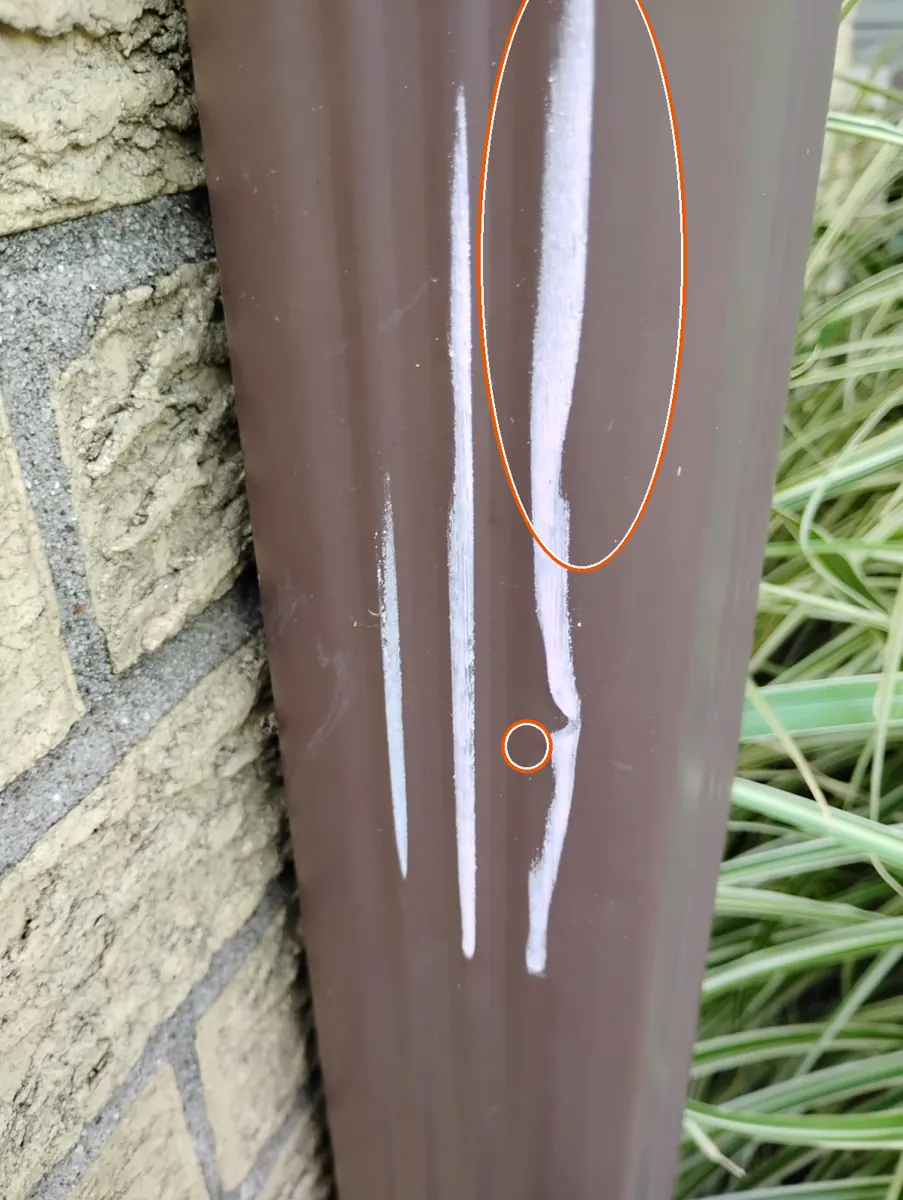
Think you have the same thing? Check your roof
Local Contractor, Not a Storm Chaser
C&N Construction runs from 24 N Hillside Ave, Hillside, IL 60162. Permanent office, not a PO box. Licensed and insured in Illinois since 2015. Over 25,400 projects completed across Chicagoland with in-house W-2 crews. When we give you a warranty, we're still here to honor it.
Sources and Date Checked
Each carrier, statute, or rule statement on this page comes from one of the sources below. We re-checked every link on the date shown. Policy wording varies by form, state, and endorsement, so your own policy controls.
- 50 Ill. Adm. Code 919.50, Required practices for all insurance companies , checked October 22, 2026
- 215 ILCS 5/154.6, Acts constituting improper claims practice , checked October 22, 2026
- 50 Ill. Adm. Code 919.80, Required claim practices (partial-loss estimates, actual cash value, tolling notice) , checked October 22, 2026
- 215 ILCS 5/143.1, Periods of limitation tolled , checked October 22, 2026
- Illinois Department of Insurance, Understanding the Consumer Complaint Process , checked October 22, 2026
- Illinois Department of Insurance, Disasters (what to do before, during and after a disaster) , checked October 22, 2026
- Illinois Department of Insurance, 2025 Consumer Complaints Ratio Report (homeowners table) , checked October 22, 2026
- State Farm, Home & Property Claims , checked October 22, 2026
- State Farm, Roof Claims , checked October 22, 2026
- State Farm, Select Service Home Repair Program , checked October 22, 2026
- State Farm Simple Insights, Understanding Replacement Cost vs Market Value (Apr. 16, 2026) , checked October 22, 2026
- Sproull v. State Farm Fire & Casualty Co., 2021 IL 126446 (Ill. Sept. 23, 2021) , checked October 22, 2026
Frequently Asked Questions
Why did State Farm deny my roof claim?
How long does State Farm have to explain a denial in Illinois?
Is a low State Farm payment the same as a denial?
Can State Farm depreciate labor on an actual cash value roof payment in Illinois?
Do I have to use State Farm's Select Service contractors?
Where do I file a complaint about a State Farm roof claim in Illinois?
Can a roofer get State Farm to reverse a denial?
Get the Roof Documented
Before You Reply to State Farm
Free Haag-certified inspection and a photo report you keep. No obligation, nothing to sign.